Rethink Retirement: 401(k) vs. IUL Benefits
Retirement Planning, 401k Limitations, IUL Benefits
Did You Know 401(k) Is Only a Tax Code? Rethinking Retirement with IUL
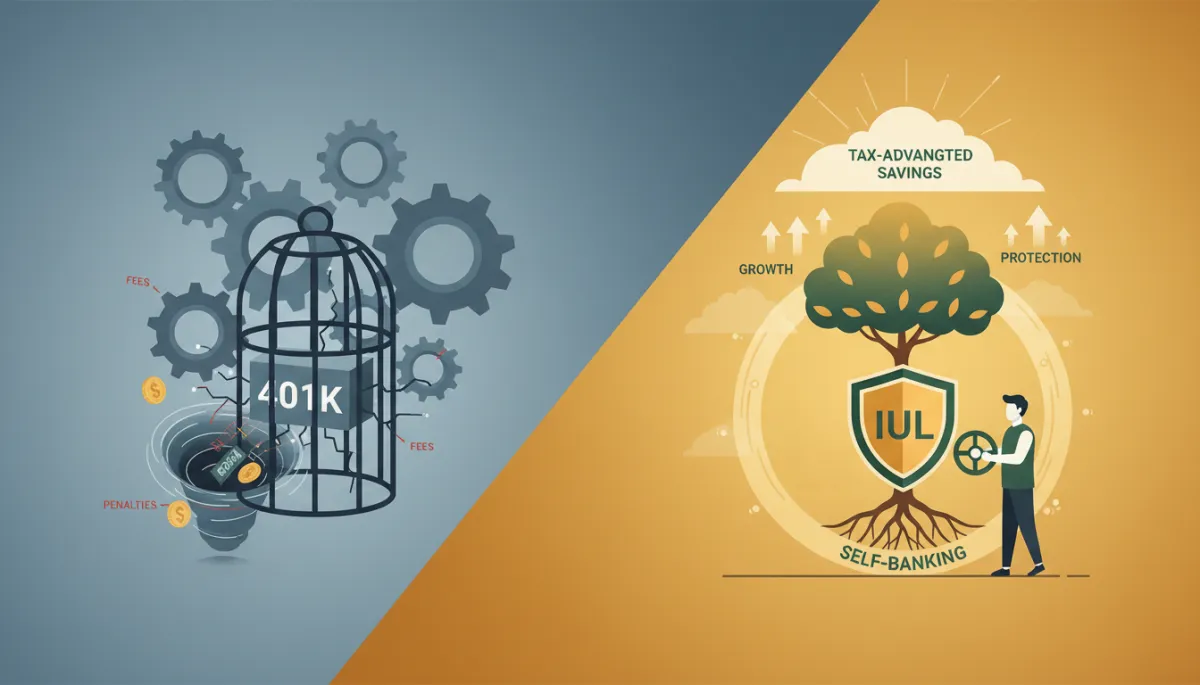
Many professionals assume their 401(k) is the gold standard for retirement planning. Yet few realize that “401(k)” is simply a section of the IRS tax code, not a promise of security. It’s a useful tool, but it also comes with crushing limitations, financial penalties, and future tax uncertainty. That’s why more families are exploring tax-advantaged savings options like Indexed Universal Life (IUL), which can provide protection, flexibility, and powerful self-banking strategies when structured correctly.
401(k): A Tax Code with Built-In Limitations
A 401(k) is not an investment in itself. It is a tax-qualified account defined by IRS Code Section 401(k). The government sets the rules: how much you can contribute, when you can access funds, and how distributions are taxed. While employer matches can be valuable, the structure often hides significant 401k limitations that matter over a lifetime:
Contribution caps: Annual limits may prevent high earners from saving as aggressively as they’d like in a tax-advantaged way.
Required minimum distributions (RMDs): At a certain age, you must start withdrawing—even if you don’t need the money—triggering taxable income.
Limited control: Investment menus are often narrow, with market exposure that can amplify losses near retirement.
The Hidden Cost: Penalties, Fees, and Future Taxes
One of the most overlooked aspects of 401(k) plans is the potential for financial penalties and layered fees. Withdraw before age 59½, and you may face a 10% early-withdrawal penalty plus ordinary income tax. Need money during a job change or emergency? A misstep can trigger a costly tax bill at the worst possible time.
Then there are the ongoing plan fees—administrative charges, fund expenses, and advisory costs—that quietly erode returns. Even more concerning, every dollar saved in a traditional 401(k) is tax-deferred, not tax-free. You’re postponing the tax bill to an unknown future rate. If tax rates rise, your “nest egg” may buy far less than you expect.
💡 Consider this: If most of your retirement assets are in tax-deferred accounts, you may be entering retirement with a silent partner—the IRS—whose share is not yet determined.
IUL: A Tax-Advantaged, Loss-Protected Alternative
An Indexed Universal Life (IUL) policy is first and foremost a life insurance contract, but when designed properly, it can also serve as a powerful tax-advantaged savings vehicle. Unlike a 401(k), an IUL is not governed by the 401(k) tax code and therefore avoids many of its structural constraints. Key IUL benefits include:
Loss protection: Cash value growth is tied to market indexes, but with a floor that protects you from market losses in down years (subject to product terms and caps).
Tax-advantaged access: When structured and managed correctly, policy loans and withdrawals can provide tax-advantaged income in retirement.
Permanent protection: A death benefit designed to protect your family, your mortgage, and your legacy, not the bank.
Properly structured IULs can blend protection, savings, and flexibility in one plan.
Self-Banking Strategies: Accessing Your Money on Your Terms
One of the most compelling aspects of IUL for professionals is the potential for self-banking strategies. As your policy’s cash value grows, you can access it through policy loans to fund major needs—college, business opportunities, or supplemental retirement income—without the rigid rules of a 401(k). Instead of asking a bank for permission, you’re effectively borrowing against your own asset.
While loans must be managed responsibly and interest will apply, your underlying cash value can continue to earn indexed interest, depending on the product design. This can create a unique balance of liquidity, growth potential, and protection that traditional retirement accounts cannot easily match.
Integrating IUL into a Holistic Retirement Plan
This isn’t about abandoning your 401(k). Employer matches and simple payroll deductions can still play a valuable role. Instead, it’s about acknowledging 401k limitations and diversifying your retirement planning so you’re not fully dependent on one tax code and one market-driven account type.
By pairing a traditional plan with a well-designed IUL, you may:
Reduce future tax exposure by creating multiple tax-advantaged income streams.
Protect your family with permanent life insurance that can help cover the mortgage and living expenses.
Gain flexible access to funds without the harsh financial penalties typical of early 401(k) withdrawals.
How Lifeworthy LLC Helps You Compare Your Options
At Lifeworthy LLC, we specialize in mortgage protection and life coverage that puts your family first. Unlike PMI, which primarily protects the bank, our solutions are designed so that benefits go directly to your loved ones in the event of illness, disability, or death. When exploring IUL benefits as part of your retirement strategy, we shop premier carriers to find structures that emphasize tax-advantaged savings, loss protection, and long-term flexibility.
Our approach is professional, caring, and no-pressure. We walk you through how an IUL might complement your existing 401(k), highlight potential financial penalties to avoid, and help you design coverage that supports both your mortgage and your long-term financial liberty.
📌 Key Takeaway: A 401(k) is just one tool, defined by a tax code. An IUL, when properly structured, can add protection, flexibility, and tax advantages your 401(k) alone may never provide.
Ready to Look Beyond the Tax Code?
If you’re a professional who has diligently contributed to a 401(k), you’ve taken an important step. Now it may be time to ask a deeper question: Is my retirement built on a tax code, or on a truly resilient strategy? Exploring IUL and self-banking strategies doesn’t mean abandoning what you’ve built—it means strengthening it with additional layers of protection and flexibility for your family’s future.
To see how an IUL could fit alongside your current retirement plan and mortgage protection, Book Your Free Quote Comparison Call with Lifeworthy LLC. We’ll help you compare top carriers, clarify your options, and design a plan that delivers the peace of mind and financial liberty your family deserves.
