Protect Your Family, Not Just the Bank
Mortgage Protection, Family Financial Security
PMI Only Protects the Bank. Here’s What Actually Protects Your Family.
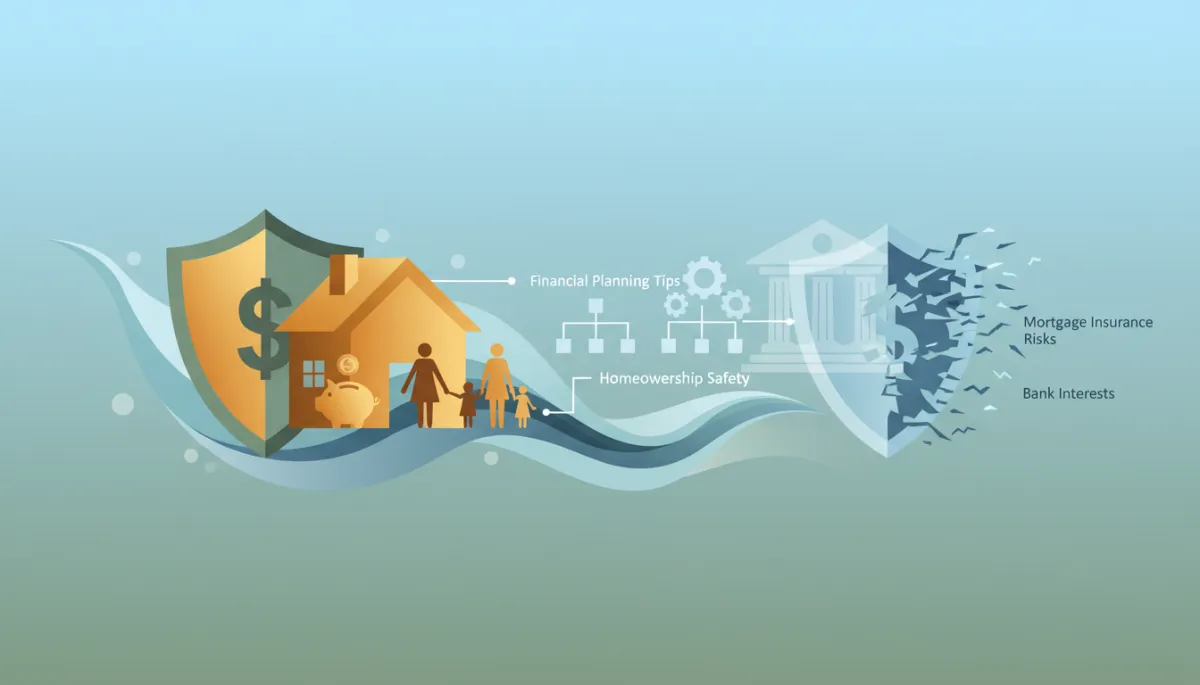
As a busy professional, you work hard to build stability, pay down your mortgage, and create lasting family financial security. Yet many homeowners mistakenly believe that Private Mortgage Insurance (PMI) is part of that safety net. It isn’t. PMI protection is designed to safeguard the lender’s balance sheet, not your loved ones’ future.
PMI Protection: Why It Exists—and Who It Really Serves
PMI is typically required when you put less than 20% down on a conventional mortgage. Its purpose is simple: protect the lender from loss if you stop making payments and the home must be foreclosed and sold at a loss. In other words, PMI is about bank interests, not household security.
Here are the core mortgage insurance risks professionals often overlook:
You pay the premiums, but the benefit goes to the bank, not your family.
PMI does not cover income loss, disability, or medical crises that cause missed payments.
If you pass away, PMI will not write a check to your spouse or children.
From a purely financial standpoint, PMI is a cost of borrowing, not a pillar of homeownership safety. It keeps the bank whole; it does not keep your family in the home if life takes an unexpected turn.
What Actually Protects Your Family and Your Home
True protection is simple: if something happens to you, money needs to flow to your family—not to the lender. That’s where tailored mortgage protection and life insurance come in. Unlike PMI, these solutions are designed around family financial security and flexibility.
Mortgage protection coverage can pay a lump sum or monthly benefit directly to your family to keep the mortgage current if you die, become ill, or are disabled.
Life insurance can cover the mortgage and provide extra funds for education, living expenses, or caregiving needs.
Benefits are paid to the people you choose, so your loved ones decide whether to pay off the home, downsize, or invest.
Direct-to-family benefits create real security when income or health is at risk.
Financial Planning Tips for Busy Professionals
As a professional juggling career demands and family responsibilities, you need clear, efficient financial planning tips that protect what matters most:
Know what you’re paying for. Review your mortgage statement and identify exactly how much is going toward PMI protection that benefits the lender only.
Stress-test your income. Ask: “If my income stopped for six months, could we keep the home?” If the answer is no, prioritize coverage that replaces income or pays the mortgage.
Align coverage with your mortgage timeline. Structure mortgage protection or term life to match your remaining mortgage years and balance.
Choose flexibility over restrictions. Look for plans that pay your family directly upon illness, disability, or death, giving them options instead of locking benefits to the bank.
How Lifeworthy LLC Puts Your Family First
At Lifeworthy LLC, our focus is simple: protect families, not lenders. As an independent insurance brokerage specializing in mortgage protection and life coverage, we compare premier carriers to find solutions that support long-term homeownership safety and genuine peace of mind.
Our no-pressure consultations are designed for professionals who value clarity, efficiency, and integrity. We walk through your mortgage, income, and goals, then recommend coverage that sends money where it belongs—straight to your family—when life doesn’t go according to plan.
📌 Key Takeaway: PMI only protects the bank. Your family deserves a plan that protects their lifestyle, their choices, and their home.
If you’re ready to turn lender-focused PMI payments into a strategy centered on your loved ones, now is the time to explore your options. Book Your Free Quote Comparison Call with Lifeworthy LLC and see, in minutes, how mortgage protection that pays your family directly can transform your security plan.
