Build Financial Security with Indexed Universal Life
Insurance, Indexed Universal Life, Financial Security
How Indexed Universal Life Builds Comprehensive Financial Security
For professionals balancing family responsibilities, a mortgage, and long‑term financial goals, Indexed Universal Life (IUL) can be a powerful, flexible tool. At Lifeworthy LLC, we help families understand how IUL’s unique combination of protection and growth can support lasting financial security.
What Is Indexed Universal Life?
Indexed Universal Life (IUL) is a type of permanent life insurance that combines lifelong coverage with the potential for cash value growth linked to a market index, such as the S&P 500. Unlike investing directly in the market, your cash value tracks the index through a crediting formula, not by purchasing actual equities. This structure allows you to participate in a portion of market gains while maintaining important protections against loss.
For families working with Lifeworthy LLC, IUL often serves as a cornerstone strategy: it offers protection for the mortgage and income, while also building a reserve that can support retirement, education funding, or other long‑term goals.
Core Advantages of IUL Benefits
The advantages of IUL benefits extend well beyond traditional term insurance. While term coverage focuses solely on a death benefit for a set period, IUL provides a more comprehensive suite of features:
Lifelong coverage designed to last as long as you maintain sufficient cash value and premiums.
Flexible premiums that can be adjusted within policy limits to match changing income and cash‑flow needs.
Cash value accumulation that can support future goals, emergencies, or supplemental retirement income.
These advantages make IUL particularly attractive for professionals who want both protection and the potential for long‑term, tax‑advantaged growth inside the same policy.
Tax‑Free Growth and Tax‑Advantaged Access
One of the most compelling features of IUL is its potential for tax‑free growth inside the policy. Cash value accumulates on a tax‑deferred basis, meaning you do not pay current income tax on credited interest or index‑linked gains as long as they remain in the policy. Over time, this can significantly enhance the compounding effect compared with taxable accounts.
In addition, many policyholders can access their cash value later in life through withdrawals to basis and policy loans. When structured and managed properly, these can provide tax‑advantaged or even tax‑free supplemental income, for example during retirement. At Lifeworthy LLC, we emphasize careful design and ongoing review to help ensure that distributions are aligned with IRS guidelines and that the policy remains in good standing.
Downside Protection in Volatile Markets
Unlike direct equity investments, IUL includes built‑in downside protection. Most IUL policies offer a minimum interest crediting rate, often referred to as a “floor,” typically at 0%. This means that when the underlying index performs poorly, your credited interest for that period will not fall below the floor (though policy charges and fees still apply).
In strong market years, your cash value may receive interest credits up to a specified cap or participation rate. In down years, the floor helps shield your accumulated value from market‑driven losses. For families relying on their policy as part of a mortgage protection or retirement strategy, this balance between growth potential and protection can offer meaningful peace of mind.
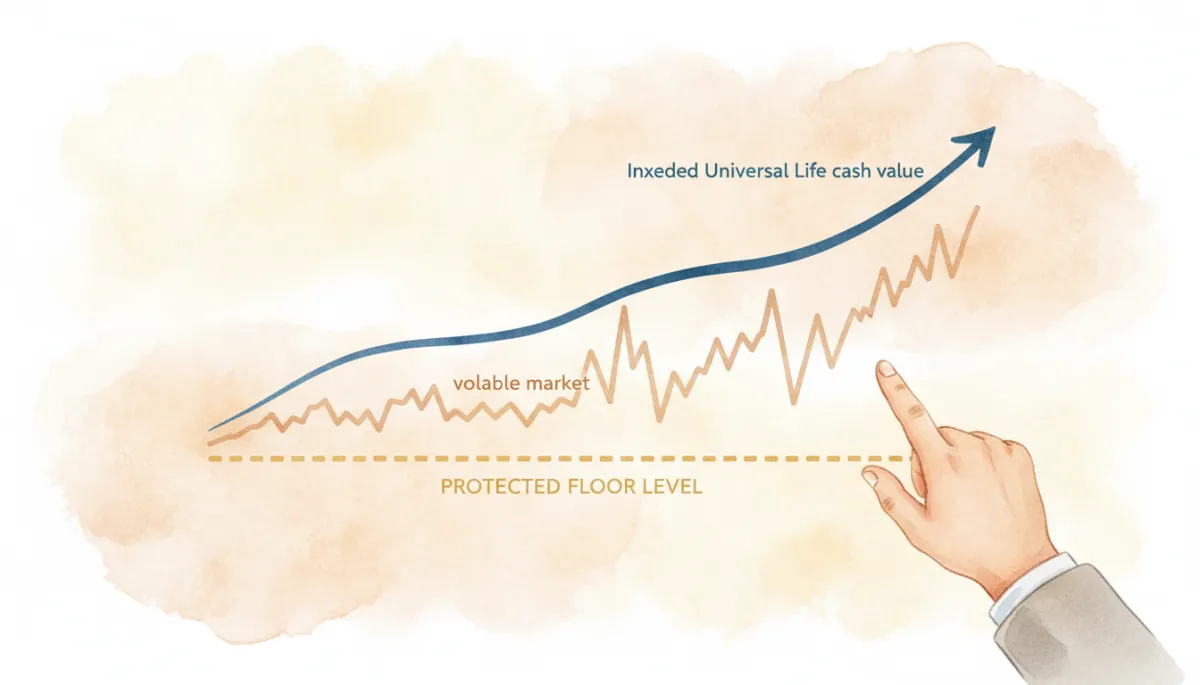
IUL’s floor feature helps preserve accumulated value during market downturns while still allowing upside potential.
The Power of the Death Benefit
At its core, an IUL is still life insurance, and the death benefit remains a central advantage. If the insured passes away, the policy’s beneficiaries receive an income‑tax‑free lump sum (under current tax law) that can be used to:
Pay off or significantly reduce a mortgage, protecting the family home.
Replace lost income, helping loved ones maintain their standard of living.
Cover education costs, debts, or final expenses without liquidating other assets.
Lifeworthy LLC focuses on solutions where the death benefit is structured to pay the family directly, rather than a lender, so your loved ones have the flexibility to choose how best to use the funds at a difficult time.
Living Benefits: Protection You Can Use While Alive
Modern IUL policies often include or can add living benefits—features that allow you to access a portion of the death benefit while you are still alive if you experience a qualifying event. Depending on the carrier and policy, these riders may provide funds in the event of:
Critical illness, such as certain cancers or heart conditions.
Chronic illness, when you are unable to perform specified activities of daily living.
Terminal illness, providing early access to funds to manage care and expenses.
These living benefits can help cover medical costs, replace income during recovery, or simply provide financial breathing room when health challenges arise. For families concerned about illness, disability, and mortgage obligations, this added layer of protection can be especially reassuring.
How IUL Features Work Together for Comprehensive Security
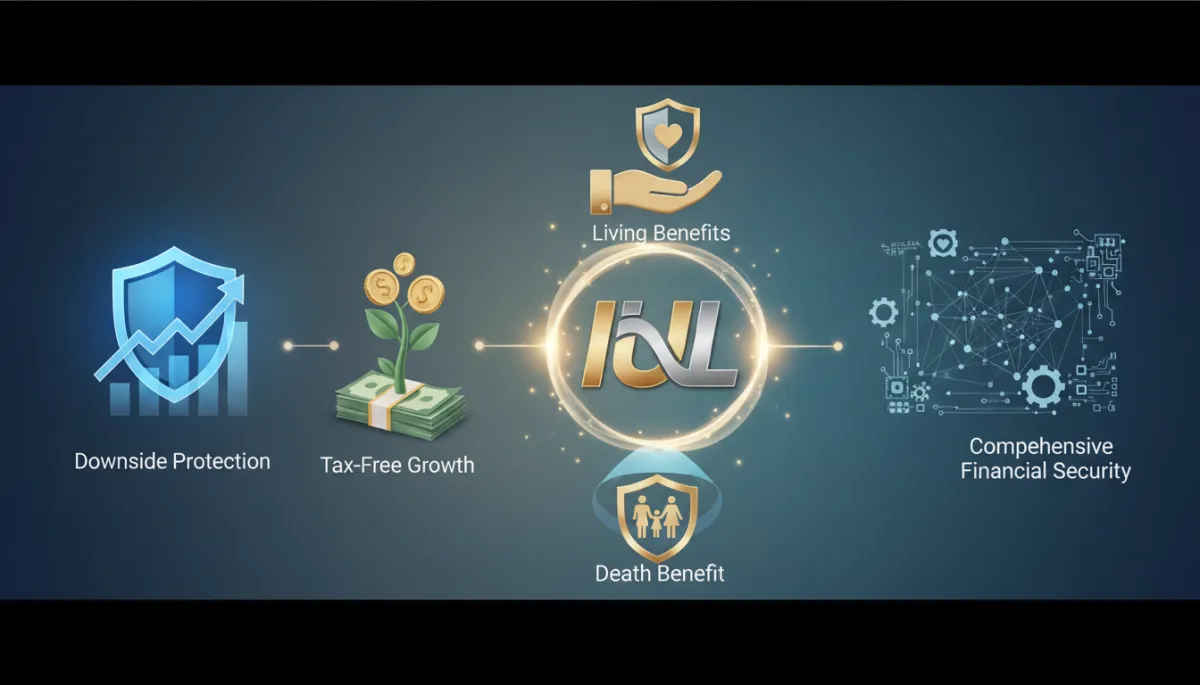
The true strength of Indexed Universal Life lies in how its features integrate to create comprehensive financial security:
Protection today: The death benefit safeguards your family’s home, lifestyle, and long‑term plans if you pass away prematurely.
Resilience during crisis: Living benefits and accessible cash value can provide funds if illness, disability, or unexpected hardship disrupts income.
Long‑term opportunity: Tax‑free growth potential, combined with downside protection, supports steady accumulation that can complement retirement and other investments.
Instead of purchasing separate products for life insurance, emergency reserves, and supplemental retirement income, an appropriately designed IUL can coordinate these functions within a single, adaptable policy. Lifeworthy LLC works with premier carriers to compare structures, riders, and costs so that each client’s IUL strategy aligns with their mortgage balance, income, family size, and long‑term objectives.
Is an IUL Right for Your Family?
Indexed Universal Life is not a one‑size‑fits‑all solution. It must be carefully tailored, funded appropriately, and reviewed regularly. For many professionals, however, the combination of IUL benefits—tax‑free growth potential, downside protection, a meaningful death benefit, and practical living benefits—can create a powerful framework for long‑term security and financial liberty.
If you are exploring ways to protect your mortgage, safeguard your family, and build a flexible pool of future resources, a well‑structured IUL may deserve a place in your plan. Lifeworthy LLC is committed to no‑pressure, education‑first conversations that put your family’s interests and peace of mind at the center of every recommendation.
Next Step: To see how an Indexed Universal Life policy could fit into your mortgage protection and long‑term security strategy, Book Your Free Quote Comparison Call with Lifeworthy LLC and review instant comparisons from top carriers.
