Annuities for Retirement: Secure Your Future
Retirement Planning, Annuities, Financial Security
Annuities Explained Simply: Peace of Mind for Retirement
For many busy professionals, retirement planning sits on a growing to‑do list. You know you should prepare, but market swings, complex investment options, and limited time make it easy to postpone decisions. Annuities can be a straightforward way to turn savings into predictable retirement income and greater financial security, without needing to monitor the market every day.
What Are Annuities, in Plain Language?
An annuity is a contract with an insurance company. You contribute money—either all at once or over time—and in return the insurer promises to provide income in the future, often for as long as you live. Think of it as transforming a portion of your savings into a personal pension that is designed to last through retirement.
Unlike many short-term investment options, annuities are built around stability and predictable retirement income. They are not meant to replace your 401(k), IRA, or brokerage account, but to complement them by covering essential expenses—housing, utilities, healthcare—so market volatility is less likely to disrupt your lifestyle.
How Annuities Support Financial Security
Financial security in retirement is about more than having a large account balance. It is about knowing your income will reliably cover your needs, even if you live longer than expected or markets underperform. This is where annuities can play a powerful role. Because they are issued by insurance companies, they include guarantees—based on the claims-paying ability of the carrier—about future payments.
Guaranteed income: Many annuities can provide payments for life, reducing the risk of outliving your savings.
Tax-deferred growth: Money inside an annuity can grow tax-deferred, potentially boosting long-term retirement planning results.
Customization: You can choose options that align with your risk tolerance and time horizon.
💡 Pro Tip: Consider using annuities to cover essential expenses, and use other investments for discretionary goals like travel or hobbies.
Key Types of Annuities and Investment Options
Not all annuities are the same. Understanding the main categories helps you see how they fit into your broader investment options and retirement strategy.
Fixed annuities: Offer a guaranteed interest rate for a set period and predictable future payments. These appeal to professionals who value stability and clear numbers over chasing higher returns.
Indexed annuities: Link potential growth to a market index, such as the S&P 500, while typically providing downside protection. They can balance growth potential with a measure of security.
Immediate annuities: You convert a lump sum into income that starts almost right away—useful if you are close to or already in retirement and want to lock in payments.
Each of these investment options involves trade-offs between liquidity, growth potential, and guarantees. A thoughtful retirement planning conversation should explore how much flexibility you need versus how much guaranteed retirement income will give you genuine peace of mind.
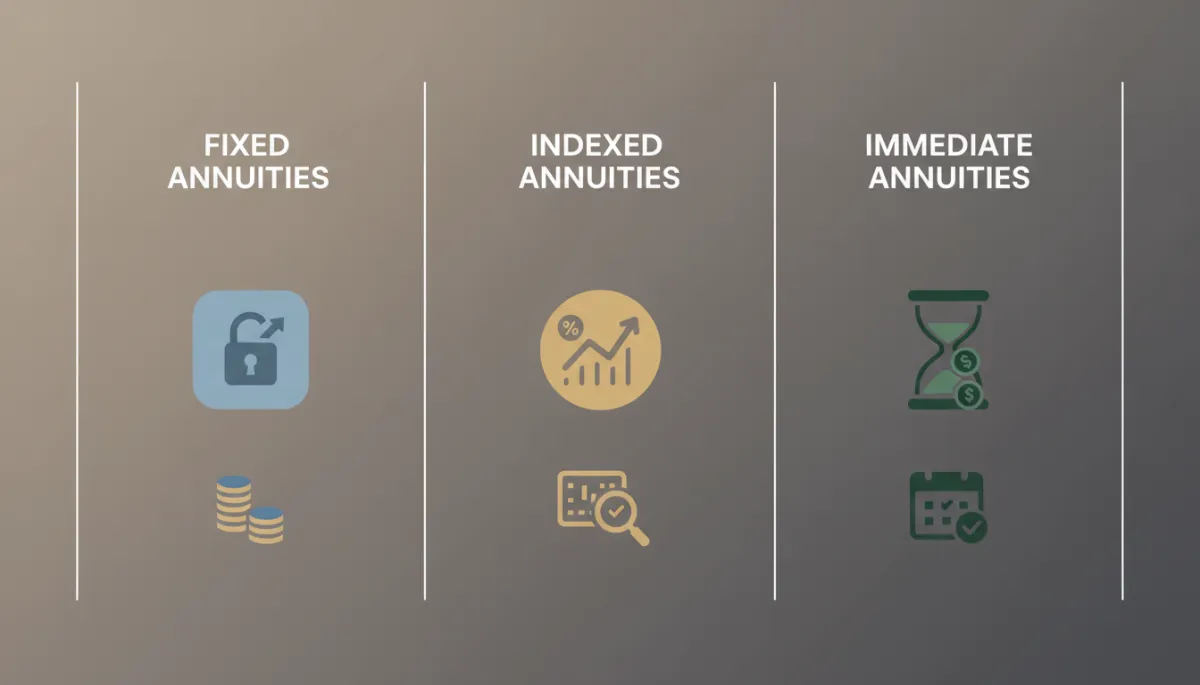
Align annuity types with your risk tolerance, time horizon, and income needs.
Peace of Mind for You and Your Family
For many families, the greatest benefit of annuities is emotional, not just financial. Knowing that a portion of your retirement income is guaranteed can ease the pressure to time the market, pick winning stocks, or constantly adjust your portfolio. It can also reduce the burden on your spouse or children, who might otherwise worry about supporting you if markets decline at the wrong time.
At Lifeworthy LLC, we see annuities as one part of a broader protection strategy that also includes mortgage protection and life insurance. When your home, income, and loved ones are protected, it becomes easier to focus on your career, your health, and the moments that matter most. That is the kind of peace of mind a well-structured plan can deliver.
Integrating Annuities Into Your Retirement Planning
The right question is rarely “Should I buy an annuity?” but rather “How much guaranteed income do I want, and from which sources?” Social Security, pensions (if available), and annuities can work together to create a base layer of income. Your other investments can then focus on growth, legacy, and lifestyle upgrades.
Estimate your essential monthly expenses in retirement—housing, food, insurance, and healthcare.
Compare that number with expected guaranteed income from Social Security and any pensions.
Consider using annuities to close any gap so those essentials are fully covered.
This approach can help you move from uncertainty to clarity. Instead of hoping your savings will last, you can see a concrete plan for lifetime retirement income, aligned with your tolerance for risk and your family’s long-term needs.
Take the Next Step With a No-Pressure Conversation
Annuities are not one-size-fits-all, and they are not right for every situation. The details—fees, riders, payout options—matter. That is why working with a trusted, independent brokerage is so important. Lifeworthy LLC shops premier carriers on your behalf, comparing protection and retirement income solutions designed to support lasting family security, not a quick sale.
If you are a professional looking to protect your mortgage, safeguard your family, and build reliable retirement income, a brief conversation can clarify your options. In just one call, you can see how annuities, life insurance, and mortgage protection might work together to provide genuine financial security and peace of mind.
📌 Next Step:Book Your Free Quote Comparison Call with Lifeworthy LLC to explore customized annuity and protection strategies that fit your life, your family, and your retirement goals.
